
By Anurag Panchal | Global Finance | Last reviewed 21 October 2026. Next review: January 2027.
Dual tax Residency: the problem in one paragraph
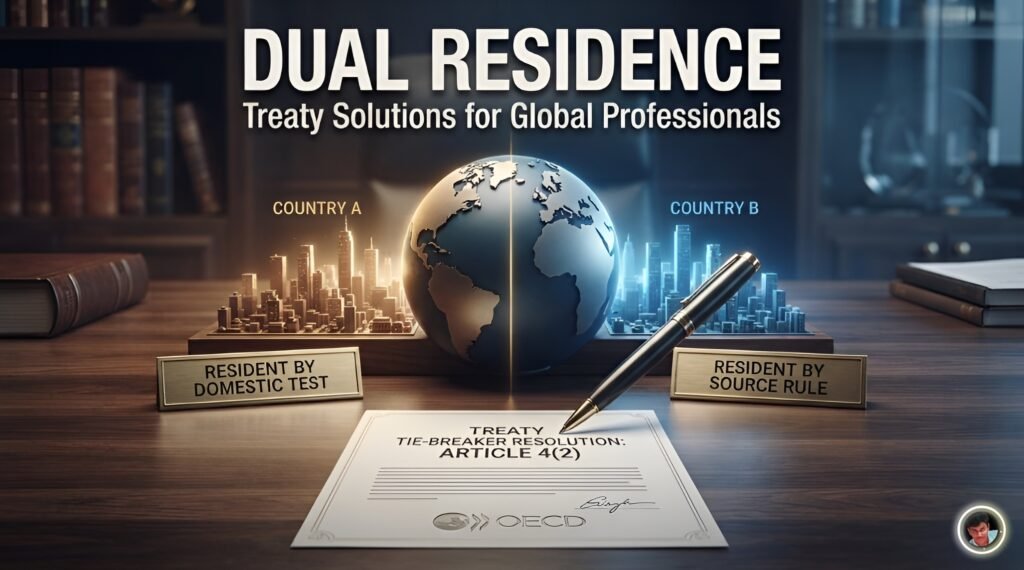
You invoice a client in another country, the money arrives, and later you discover that two governments each treat you as their tax resident. This is dual tax residency: both countries claim tax on your worldwide income, and nobody coordinates it, because there is no global register of tax residents and every country writes its own test. Unless you act, you can end up paying tax twice on the same income.
The way out is written into the law. A tax treaty’s tie-breaker rules decide which country is your residence for treaty purposes, and a foreign tax credit or exemption relieves tax already paid abroad. Neither happens automatically: you have to prove your residency and claim the relief.
This guide gives you one framework that works for any country pair, the exact residency tests of India, the US, the UK, Germany, France, China and Japan as of 21 October 2026, the treaty tie-breaker order, a worked credit formula, and a 7-step checklist you can run every year.
Educational content, not tax advice. Tax residency rules are written by each country and treaties differ from one another. Always confirm your own facts against the official source and, for large amounts, with a qualified tax professional in the countries involved.
Key takeaways
- Residency is not citizenship. Each country decides residency by its own law. The United States is the major exception because it also taxes citizens on worldwide income.
- Double tax comes in two different types, and each has a different cure (see the next section).
- There is no universal “183-day rule”. Countries use day counts, homes, one-year stays and economic ties, and they count days differently.
- Treaties are the cure for dual residency, but only if a treaty exists between the two countries, you can prove your residency, and you claim the benefit.
- Paying tax abroad does not automatically cancel tax at home. The relief (credit or exemption) must be claimed.
The two types of double taxation (this is the framework)
The two types of double taxation (this is the framework)
| Feature | Type A: Dual residence | Type B: Residence vs source |
|---|---|---|
| What happens | Two countries both treat you as resident, so both tax worldwide income | One country taxes you as resident, another taxes the income because it arises there |
| Typical trigger | A home in one country plus a long stay (182/183+ days) or a home in another | A client’s country withholds tax on payments to you |
| The cure | Treaty tie-breaker (OECD Model Article 4(2)) decides one residence | Credit or exemption for foreign tax (OECD Model Articles 23A/23B) |
| Evidence needed | Facts on home, family, economic ties, days | Proof of foreign tax paid, plus a residency certificate |
← Swipe left or right to see the full table →
Most blogs mix these up. Keep them separate and the rest of the topic becomes simple.
Step 1: How countries decide who is a resident
Countries use four families of tests. Many use more than one.
- Day count: how many days you were physically present.
- Home: whether you have a dwelling available to you.
- Duration: how long you have stayed or lived there.
- Ties and economic centre: where your family, work and wealth are.
Rules snapshot as of 21 October 2026
Rules snapshot as of 21 October 2026
| Country | Tax year | Main residency test(s) |
|---|---|---|
| India | 1 Apr to 31 Mar | 182+ days in the tax year, or 60+ days in the year and 365+ days in the preceding 4 years (with exceptions below) |
| United States | Calendar year (most individuals) | Green card test, or the Substantial Presence Test (weighted 3-year formula, below) |
| United Kingdom | 6 Apr to 5 Apr | Statutory Residence Test: automatic overseas tests, automatic UK tests, then sufficient ties |
| Germany | Calendar year | A dwelling you keep and use (Wohnsitz, §8 AO), or habitual abode (gewöhnlicher Aufenthalt, §9 AO): a continuous stay of more than six months |
| France | Calendar year | Any one of: home or main place of stay in France; non-incidental professional activity in France; centre of economic interests in France (Art. 4 B CGI) |
| China | Calendar year | Domicile in China, or 183+ days in a calendar year |
| Japan | Calendar year | Domicile (jusho), or a residence (kyosho) for one year or more. A job expected to last a year or more can make you resident from arrival. |
← Swipe left or right to see the full table →
Notice that three of these seven (Germany, France, Japan) have no simple “183 days in a year” test. Germany and Japan use a home or a continuous stay, and France uses a home, work or economic centre. This is why people who “stayed under 183 days” still end up resident.
India in detail
India’s Income-tax Act, 2025 came into force on 1 April 2026 and replaced the 1961 Act. For residency, Section 6 keeps the same day-count logic, and the new Act speaks of a “tax year” instead of previous year and assessment year. Tax year 2025-26 and earlier remain under the 1961 Act.
- Resident: 182+ days in the tax year (s.6(2)(a)), or 60+ days in the tax year and 365+ days in the preceding 4 years (s.6(2)(b)).
- Citizen who leaves India for employment abroad, or as crew of an Indian ship: the 60-day limb does not apply, so only the 182-day test counts (s.6(3)).
- Citizen or person of Indian origin who is outside India and comes on a visit: again only the 182-day test counts (s.6(4)), unless the 120-day rule below applies.
- 120-day rule (s.6(5)): if such a visitor has total income, other than income from foreign sources, above Rs 15 lakh, the second limb applies with 120 days instead of 60 (together with 365+ days in the preceding 4 years). A person in India for 120 to 181 days in this case is resident but not ordinarily resident (RNOR) (s.6(13)(b)).
- Deemed residency (s.6(7)): an Indian citizen with income, other than income from foreign sources, above Rs 15 lakh who is not liable to tax in any other country by reason of domicile or residence is treated as resident, and as RNOR (s.6(13)(c)). It does not apply to someone already resident by day count (s.6(8)). This catches people who move to a zero-tax country.
- Income from foreign sources (s.6(14)): income that accrues outside India, except income derived from a business controlled in India or a profession set up in India. For a freelancer, invoices to foreign clients may therefore still count towards the Rs 15 lakh test if the profession is set up in India. Confirm your own case with a professional.
- ROR vs RNOR (s.6(13)): a resident is “ordinarily resident” only if resident in at least 2 of the preceding 10 years and present 730 days or more in the preceding 7 years. Otherwise RNOR.
- Why it matters: a resident (ROR) is taxed in India on worldwide income. An RNOR’s foreign income generally stays outside Indian tax unless it comes from a business controlled in India or a profession set up in India.
Residency decides what India can tax. It does not cover what happens when the payment lands. For that, read our guide on GST, FEMA and Section 58 rules for freelancers paid by US clients.
United States in detail
A person is a US tax resident if they hold a green card, or meet the Substantial Presence Test for the calendar year:
- at least 31 days in the current year, and
- at least 183 days using this weighted formula:
Weighted days = (days this year) + (1/3 × days last year) + (1/6 × days two years ago)
Worked example: 120 days in each of 2023, 2024 and 2025 gives 120 + 40 + 20 = 180, which is below 183, so not resident by this test for 2025. Now try 122 days each year: 122 + 40.67 + 20.33 = 183.0, which meets the test. For a steady yearly stay, the tipping point is 122 days, not 120 and not 183.
Want to test your own days? The IRS walks through the Substantial Presence Test step by step.
Even if you meet the test, you may avoid US residency under the closer connection exception if you were in the US fewer than 183 days in the current year, keep a tax home in a foreign country and have a closer connection to it. You claim it by filing Form 8840.
US citizens are taxed on worldwide income wherever they live. Their main relief tools are the foreign tax credit and the Foreign Earned Income Exclusion (FEIE): up to US$132,900 for 2026 (US$130,000 for 2025), available if you pass the bona fide residence test or the physical presence test (330 full days in a foreign country in any 12-month period). For freelancers, note that the exclusion does not remove US self-employment tax.
United Kingdom in detail
The Statutory Residence Test applies in a fixed order for each UK tax year (6 April to 5 April). UK days are generally counted by midnights spent in the UK.
Not sure which test applies to you? HMRC explains the Statutory Residence Test in plain steps, with examples.
- Automatically non-resident if, for example: you were resident in any of the previous 3 years and spend fewer than 16 days in the UK; or you were resident in none of the previous 3 years and spend fewer than 46 days; or you work full-time overseas, spend fewer than 91 days in the UK and work more than 3 hours on fewer than 31 days in the UK, with no significant break from your overseas work.
- Automatically resident if, for example, you spend 183 days or more in the UK (other automatic UK tests cover a UK home and full-time UK work).
- Otherwise, the sufficient ties test compares your UK days with the number of UK “ties” you have (family, accommodation, work, 90-day and country ties).
- Since 6 April 2025 the UK is residence-based and the “non-dom” regime has been abolished. New arrivals who were non-UK resident for the previous 10 consecutive tax years can claim relief on foreign income and gains for their first 4 years of UK residence, claimed through Self Assessment.
Germany, France, China and Japan: what to remember
- Germany: a dwelling you have at your disposal, in circumstances showing you will keep and use it, makes you resident from day one, however few days you spend there (§ 8 AO). Habitual abode (§ 9 AO): a continuous stay of more than six months counts as habitual abode from the first day, short interruptions ignored, with a carve-out for stays that are purely for visits, recreation, cures or similar private purposes and last no longer than one year.
- France: one criterion is enough under French domestic law (Art. 4 B CGI): a home or main place of stay in France, a professional activity in France that is not merely incidental, or the centre of economic interests in France. A freelancer who works in France on a non-incidental basis can therefore be a French tax resident whatever their home country, although a treaty can still allocate residence to the other country.
- China: resident if domiciled in China, or if not domiciled but present for 183+ days in a calendar year (IIT Law, Art. 1). Under the six-year rule, a person who is not domiciled in China is exempt on income earned abroad and paid by a foreign entity (with the required filing), unless they were present for 183+ days in each of the previous six years and never left on a single trip of more than 30 days in any of those years. A single trip of more than 30 days resets the count.
- Japan: resident if you have a domicile (jusho), or a residence (kyosho) for one year or more. “Domicile” is judged by where your base of living is. Someone who comes for a job that normally requires living in Japan for a year or more is presumed to have a domicile from arrival, unless a contract clearly fixes a stay of under one year. A non-Japanese resident with 5 years or less of domicile or residence in the preceding 10 is a non-permanent resident, taxed on Japan-source income plus foreign income paid in Japan or remitted to Japan.
Three traps in counting days
- Different tax years. India (April to March) and the UK (6 April to 5 April) do not match the calendar year used by the others. Keep a day ledger by date, then re-cut it for each country’s year.
- Different counting rules. The UK counts midnights; the US counts any part of a day unless an exclusion applies; check how arrival and departure days count in each country.
- Lookback periods. India (4 years for the 60-day limb, and 10 and 7 years for ordinary residence), the US (3 years, weighted), the UK (3 years), Japan (10 years) and China (6 years) all look backwards, so last year’s travel affects this year’s status.
Step 2: The dual tax residency tie-breaker (Type A double taxation)
When two countries both treat you as resident, a tax treaty built on the OECD Model resolves it by moving down this ladder in order, stopping at the first step that gives an answer:
- Permanent home available to you. The country where you have a home continuously available. (If you have one in only one country, you are done.)
- Centre of vital interests. If you have a permanent home in both, the country where your personal and economic relations are closer: family, social ties, work, business, where you manage your assets.
- Habitual abode. If the centre of vital interests cannot be determined, or you have a home in neither, the country where you habitually stay.
- Nationality. If you have a habitual abode in both or neither, the country of which you are a national.
- Mutual agreement. If you are a national of both or neither, the two tax authorities settle it between themselves.
Where does this ladder come from? It sits in Article 4 of the OECD Model Tax Convention, the blueprint behind most tax treaties worldwide.
Worked example (illustrative). Meera, an Indian citizen and freelance designer, keeps a rented flat in Berlin available year-round and also spends 190 days in India in the Indian tax year, where she keeps her family home available to her.
- India: 190 days is above 182, so she is resident.
- Germany: a dwelling she keeps and uses makes her resident.
- Both claim her. Assuming the India-Germany treaty follows the standard ladder, step 1 does not decide it if she has a home available in both. Step 2 looks at where her family, clients, bank accounts and business are. The answer depends on facts, which is why she must document them.
Limits you must know
- The ladder only works if there is a treaty between the two countries. No treaty means no tie-breaker.
- Treaties differ. The OECD order is a model. Some treaties vary it, so read Article 4 of the actual treaty.
- The United States keeps the right to tax its citizens and residents under a “saving clause” in most treaties, with listed exceptions. A US citizen cannot use a tie-breaker to stop being taxed by the US.
- The treaty “183-day rule” is not a residency test. In OECD Article 15(2), it applies to employment income only, counts days in any twelve-month period commencing or ending in the fiscal year, and needs all three conditions (days, employer not resident in the work country, and no permanent establishment bearing the cost). Do not confuse it with domestic residency tests.
- Freelancers should read the treaty’s article on independent personal services (in older treaties) or business profits and permanent establishment (in modern treaties), because source-country taxing rights for self-employed income differ.
Step 3: Credit or exemption (Type B double taxation)
When another country has already taxed income at source, your country of residence usually gives one of two reliefs.
- Credit method: your home country taxes the income but subtracts the foreign tax, up to a limit.
- Exemption method: your home country does not tax that foreign income (it may still use it to set your rate).
The credit limit formula
Maximum credit = Home tax on worldwide income × (Foreign income ÷ Worldwide income)
You receive the lower of the foreign tax actually paid and this maximum.
Worked example (flat rates for clarity). Worldwide income is 100,000 units, of which 10,000 comes from abroad. Your home tax rate is 30%. Home tax on worldwide income is 30,000. Maximum credit is 30,000 × (10,000 ÷ 100,000) = 3,000.
Foreign tax credit limit worked example
| Foreign tax rate | Foreign tax paid | Credit allowed | Total tax on the 10,000 |
|---|---|---|---|
| 15% | 1,500 | 1,500 | 1,500 abroad + 1,500 at home = 3,000 |
| 30% | 3,000 | 3,000 | 3,000 abroad + 0 at home = 3,000 |
| 40% | 4,000 | 3,000 | 4,000 abroad + 0 at home = 4,000 |
← Swipe left or right to see the full table →
Two lessons: a credit never reduces your tax below the home rate on that income, and when the foreign rate is higher, the excess is a real cost (whether it can be carried to other years depends on local law). Real systems use progressive brackets, so the home tax figure comes from your actual computation, but the limit works the same way.
Reducing the foreign tax in the first place
Often the better move is to prevent the over-withholding. A client’s country will normally withhold at its domestic rate unless it receives proof that you are a treaty resident. That proof is the residency certificate in the next step.
For Indian freelancers billing US clients, this is where the damage is biggest. Here is how the 30% IRS Withholding problem starts, and how the right paperwork, filed before the payment, changes the number.
Step 4: Prove your residency (the Tax Residency Certificate)
A Tax Residency Certificate (TRC) is issued by the tax authority of the country where you are resident and certifies that you are resident there for a stated period. Without it, payers and tax offices abroad generally have no basis to apply treaty rates.
- For income arising in India (you are a non-resident of India): file Form 41 electronically on the income-tax portal and upload a TRC from your country of residence (s.159(8) of the Income-tax Act 2025, Rule 75 of the Income-tax Rules 2026). The TRC must cover the relevant tax year. Form 41 replaces Form 10F and is filed once in a tax year. Without a valid Form 41, treaty benefit is not available: the payer deducts TDS at the normal rate, and income you claimed as exempt in your return is taxed at Indian rates. A PAN is optional. Income of tax year 2025-26 and earlier falls under the 1961 Act, where the equivalent declaration is Form 10F (Rule 21AB); confirm which form applies to your payment.
- For an Indian resident claiming treaty benefits abroad: Apply to the Indian Income Tax Department for a certificate of residence through the income-tax portal (application in Form 42, certificate in Form 43 under the 2026 Rules; confirm on the portal).
- For US residency certification: Apply to the IRS using Form 8802, which results in Form 6166. Apply well ahead of the payment; the IRS asks for applications at least 45 days before you need the certificate.
- Other countries: request the residency or “resident certificate” from your national tax authority. The name and process differ, and it is often issued for one calendar or tax year at a time.
If you claim a treaty position on your US return that overrides US law, disclose it on Form 8833. Dual-resident taxpayers who claim treaty non-resident status use the same form.
The Residency Audit: a 7-step annual workflow
- Log days by date in a simple sheet: date, country, reason. Include arrival and departure days.
- Re-cut the log into each country’s tax year (India Apr to Mar, UK 6 Apr to 5 Apr, others calendar year).
- Run each country’s domestic test from the table above, including lookback periods.
- Flag every country where you test as resident. Zero or one flag means no tie-breaker is needed (you may still need a credit under Step 3). Two or more means Type A.
- Apply the tie-breaker in the actual treaty, with written evidence of your home, family and economic ties.
- Obtain the TRC from your country of residence and give it to payers before the payment, not after.
- Claim relief and file. File where required, claim the credit or exemption for foreign tax, and keep the withholding statements, certificates and the day log for the period your authority requires.
Tax is only half the journey. If the money itself gets held on the way in, see our guide on FEMA B2B rules and LRS caps.
Common mistakes
- Treating citizenship as residency (it rarely is, except for the US).
- Believing “under 183 days means safe” when the country tests by home or ties.
- Keeping a home available abroad and forgetting it counts as a residence in some systems.
- Moving to a no-income-tax country and assuming India is finished with you (if you are an Indian citizen with Indian income above Rs 15 lakh, see deemed residency).
- Paying foreign tax and never claiming the credit.
- Forgetting that tax years differ between countries.
- Sending the TRC after the payment has been taxed at the full domestic rate.
- Confusing the treaty employment “183-day rule” with a residency test.
What is permanent and what changes
What is permanent and what changes
| Stable concept (changes rarely) | Time-sensitive figure (re-check every year) |
|---|---|
| Dual residency, tie-breaker order, credit formula | US FEIE amount (US$132,900 for 2026) |
| Day-count and home-based test structures | Rs 15 lakh threshold for India’s 120-day and deemed-residency rules |
| TRC as proof of residency | Form numbers and portal paths (India moved from Form 10F to Form 41 on 1 April 2026) |
| Treaty Article 4 ladder | UK foreign income and gains regime terms |
← Swipe left or right to see the full table →
Before you rely on any number in this article, check the primary source for your country: the IRS (substantial presence test and Form 8840), HMRC and legislation.gov.uk (Finance Act 2013, Schedule 45), the Indian Income Tax Department portal (Income-tax Act, 2025 and Rules, 2026), Japan’s National Tax Agency, France’s BOFiP, the German Abgabenordnung (§§ 8 and 9) and China’s State Taxation Administration.
FAQ
Q1: Can I be a tax resident of two countries at once?
Yes. Each country applies its own test, so two can both treat you as resident. A tax treaty can then decide which one prevails for treaty purposes.
Q2: Does 183 days always make me resident?
Not always. Under domestic law, 183+ days in a year makes you resident in the UK and in China (for someone not domiciled there), and India’s threshold is 182. The US uses a weighted three-year formula and allows a closer-connection exception. Germany, France and Japan can make you resident with far fewer days, through a home, work or a one-year stay. A treaty can then still decide which country prevails.
Q3: What if there is no tax treaty between my two countries?
There is no tie-breaker. Relief then depends on each country’s domestic rules, usually a unilateral foreign tax credit. Check this before you move or sign a contract.
Q4: Do I need a TRC if I am a freelancer?
If you want a reduced treaty withholding rate on payments from abroad, the payer will usually need proof of your residency. The TRC is that proof.
Q5: Is this guide enough to file my taxes?
No. It explains the framework so you ask the right questions. Your facts, the specific treaty and current law decide the result.
Reviewed on 21 October 2026 against: Income-tax Act 2025 s.6 and the Form 41, 42 and 43 guidance notes (Income Tax Department), IRS Notice 2026-25 and IRS pages on Forms 8802/6166, Form 8833 and the foreign earned income physical presence test, HMRC RDR3 (updated 11 June 2026), Germany AO §§ 8-9, France Art. 4 B CGI (BOFiP), China IIT Law Art. 1, the NTA Japan 2025 income tax guide and the OECD Model Tax Convention (2017 edition). Tax laws change; verify before you rely on them.
Legal Disclaimer
This article is published strictly for informational, educational, and research purposes and does not constitute formal tax, legal, or financial advice. International tax residency, double taxation avoidance agreements (DTAA), and cross-border compliance laws vary significantly based on individual circumstances, jurisdiction, and changing statutory amendments. Readers are strongly advised to verify their specific factual situation against official government portals or consult a qualified Chartered Accountant (CA), Certified Public Accountant (CPA), or tax attorney before making any financial decisions or tax filings. Neither the author nor the publishers accept any liability for actions taken based on the information provided in this guide.

Anurag Panchal
Founder & Chief Editor at ServiceMoney.in & AllRoundUpdate.com.
An independent freelancer and compliance researcher, this guide is built upon rigorous analysis of international taxation, global treaties, and cross-border frameworks. The goal is to demystify dual residence tax implications and OECD tie-breaker rules into clear, structured, and factual insights for remote professionals and global freelancers.
Explore our FinTech Compliance Hub for simplified breakdowns and research archives.

