
1. EXECUTIVE ABSTRACT
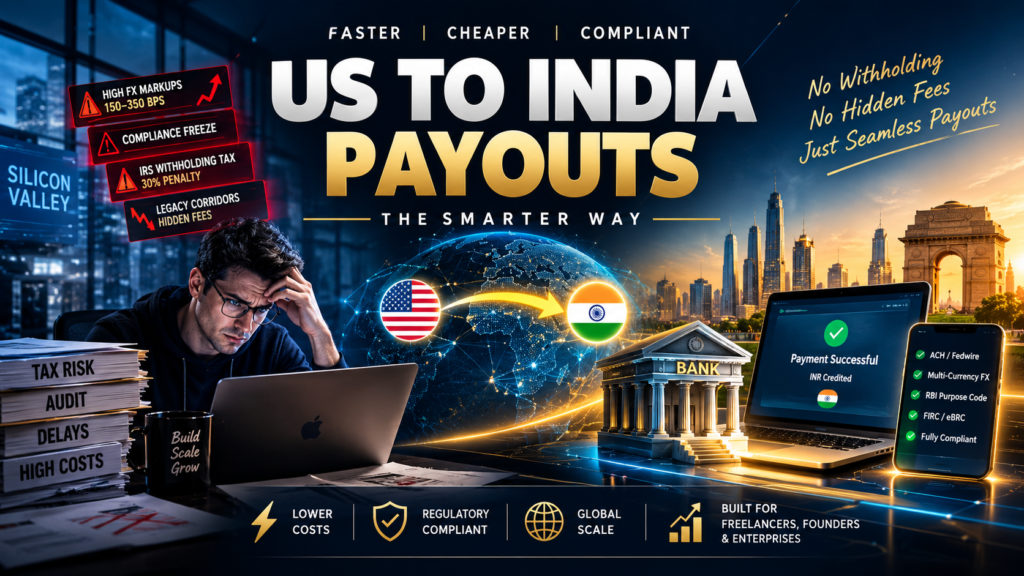
US-to-India corporate payouts scaling past critical operational thresholds face severe systemic friction under legacy payment structures, triggering arbitrary compliance freezes and uncompetitive FX markups running between 150–350 basis points. For Silicon Valley tech founders and enterprise financial controllers, executing these offshore disbursements carries a continuous balance-sheet threat: triggering an unexpected audit or failing to correctly manage the IRS Withholding Tax on Inbound India Invoices, which exposes corporate treasury to a mandatory 30% statutory penalty.
Legacy cross-border corridors systematically bleed corporate margins through hidden conversion markups. If your treasury ecosystem relies on outdated retail checkouts, you are likely losing thousands per payroll cycle. Review our comprehensive evaluation on Wise vs PayPal Payouts to analyze structural cost models before initiating your next batch file.
This operational blueprint breaks down the precise cross-border treasury framework required to legally neutralize these withholding liabilities while engineering a seamless institutional payment pipeline that dynamically scales. By shifting execution from consumer payment aggregators to localized US domestic clearing infrastructures (ACH/Fedwire parameters), outbound transfers bypass volatile retail thresholds entirely under updated RBI Payment Aggregator-Cross Border (PA-CB) mandates.
For high-ticket invoices exceeding the (~$30,000) individual PA-CB transaction cap, this architecture establishes automated ledger batching parameters to split and route payouts across wholesale bank networks seamlessly. Capital clears natively within the US banking system, converts at the precise interbank mid-market rate via multi-currency ledger routing, and enters Indian beneficiary current accounts via inward rails mapped to automated RBI Purpose Codes.
This automated protocol loop programmatically onboard-validates dual tax forms (IRS Form W-8BEN/W-8BEN-E) and guarantees instant, GST-linked eFIRA generation through the centralized PRAVAAH portal—permanently overcoming your withholding fears, preventing unilateral tax recovery actions, and ensuring airtight, dual-jurisdiction compliance across active 2026 mandates.
2. TECHNICAL ARCHITECTURE DIAGRAM
+---------------------------------------------------------------------------------+
|                      US-TO-INDIA CROSS-BORDER PAYOUT FLOW                       |
+---------------------------------------------------------------------------------+

[ Layer 1: US Outbound Initiation ]
  US Payor (SaaS Founder / Enterprise)
        │
        ▼
  Initiates USD payout via US Domestic Clearing Rails (ACH / Fedwire)

[ Layer 2: Domestic Clearing & Tax Validation ]
  Wise US Domestic Clearing Infrastructure
        │
        ├──> Absorbs funds locally via partner bank routing (No SWIFT intermediary fees)
        └──> Validates IRS W-8BEN-E onboarding status & entity tax exemption profiles

[ Layer 3: Conversion & Purpose Mapping ]
  Multi-Currency Ledger & FX Engine
        │
        ├──> Executes spot conversion at interbank mid-market rate
        └──> Maps automated RBI Purpose Code (e.g., P0102 / Software Services)

[ Layer 4: Compliance & Local Indian Clearing ]
  RBI PA-CB Compliant Indian Clearing
        │
        ├──> Routes funds via local Indian banking partners (NEFT / RTGS / IMPS)
        └──> Auto-generates electronic FIRC / e-BRC with valid IEC & PAN associations

[ Layer 5: Capital Realization ]
  Indian Beneficiary (Remote Agency / Vendor)
        │
        ▼
  Receives INR directly into current account with immutable audit trail
3. REGULATORY COMPLIANCE ANALYSIS
Executing high-ticket payouts across the US-India corridor requires reconciling divergent regulatory regimes enforced by US and Indian oversight bodies.
US Outbound Compliance Hooks (FinCEN & IRS)
- FinCEN MSB & AML Compliance: Transactions routed through domestic clearing partners operate with regulated banking rails. Ultimate Beneficial Ownership (UBO) verification (updated per 2026 FinCEN reporting mandates) and originator-beneficiary data integrity (Travel Rule thresholds) are enforced at account inception, mitigating suspicious activity reporting (SAR) flags.
Ultimate Beneficial Ownership (UBO) reporting standards require absolute structural tracking at the entity level to satisfy financial crime prevention protocols. Failure to execute precise entity verification can trigger severe operational penalties. Review the official regulatory criteria outlined in the active FinCEN Corporate Transparency frameworks to align your platform’s onboarding logic with current federal data mandates.
- IRS W-8BEN-E Onboarding & Withholding Exemption: For US corporations paying foreign corporate entities (Indian private limited companies, LLPs, or sole proprietorships rendering services outside the US), withholding agent liability under Section 1441/1442 is eliminated by securing a verified, digitally signed, and currently valid (3-year expiration monitored) Form W-8BEN-E. This certifies foreign status and claims complete exemption from 30% US backup withholding under applicable Double Taxation Avoidance Agreements (DTAA).
🇺🇸 US-to-India Cross-Border Payout Tool 🇮🇳
Compare real-time exchange rates and hidden transfer fees
Indian Inbound Compliance Hooks (RBI, FEMA, & GST)
Inbound commercial remittances entering the domestic ledger frequently hit localized compliance triggers due to misaligned bank parameters. Before deploying your transaction nodes under the current framework, map your technical path using our blueprint on Fixing US-to-India Bank Holds to secure seamless Authorized Dealer clearances.
- RBI Payment Aggregator - Cross Border (PA-CB) Mandates: Inbound remittances are strictly aligned with the new FEMA (Export and Import of Goods and Services) Regulations, 2026, ensuring compliance via RBI-authorized PA-CB (Payment Aggregator-Cross Border) channels. All reporting and validations are synchronized through the PRAVAAH portal within the mandated 9-month realization window.
- Purpose Code Identification & FIRC Issuance :- Inbound remittances are matched with the appropriate RBI-mandated Purpose Codes at inception. Under the FEMA (Export and Import of Goods and Services) Regulations, 2026, the standard realization window for service exports is strictly capped at 9 months from the invoice date. Electronic Foreign Inward Remittance Certificates (e-FIRC) or settlement advices are auto-generated via integrated PA-CB (Payment Aggregator - Cross Border) banking rails and mapped to the PRAVAAH portal to ensure zero-error regulatory reconciliation.
- GST & Export of Services Alignment :- Outbound payouts qualify as Zero-Rated Supplies under Section 16 of the IGST Act, backed by a valid Letter of Undertaking (LUT). In alignment with the Finance Act 2026 amendments, the place of supply rules (specifically regarding Intermediary Services under Section 13) ensure full exemption from GST, provided foreign inward remittance is realized within the FEMA-mandated 9-month timeframe. Transactions exceeding statutory thresholds strictly comply with real-time GST E-Invoicing (IRN and QR Code generation) mandates for 2026
4. DATA COMPARISON MATRIX
| Operational Parameter | Legacy Gateways (PayPal, Payoneer OPGSP) | Wise Local US Clearing + PA-CB Rail |
| Settlement Velocity | 3 to 7 Business Days (Subject to rolling reserves) | Same-day or Next-Day (T+0 / T+1 clearing) |
| Hidden FX Markups | 150 to 350 bps over interbank mid-market rate | Zero markup; transparent mid-market rate + flat fee |
| Transaction Value Caps | Strict $10,000 per-transaction OPGSP retail limits | Up to ($30,000) per transaction as per RBI PA-CB norms |
| FIRC Automation | Manual, delayed, or subject to heavy intermediary fees | Automated Digital FIRA / Partner AD-1 Bank e-FIRC Support |
| Audit Trail Integrity | Fragmented merchant-of-record statement entries | Immutable transaction logs mapped to exact purpose codes |
5. STEP-BY-STEP OPERATIONAL BLUEPRINT
- Treasury Account Provisioning: Establish an institutional multi-currency account structure with local routing capabilities (US ACH/Wire transit numbers) to decouple outbound capital from high-cost SWIFT networks.
- Tax Identity & Beneficiary Onboarding :- Collect and cryptographically validate appropriate IRS tax forms—Form W-8BEN for individual contractors/freelancers and Form W-8BEN-E for entities—from Indian beneficiaries prior to initiating disbursement workflows, anchoring the tax-exempt or reduced withholding status in the payment ledger.
- Withholding agents are legally bound to enforce rigid document validation protocols to maintain complete backup withholding immunities under cross-border trade treaties. Mismanaging foreign vendor identity certificates immediately exposes the domestic ledger to compliance reviews. Access the institutional legal parameters detailed in the official IRS Withholding Agent Regulations to eliminate your platform's corporate statutory liability loops before capital deployment.
- Purpose Code Taxonomy Mapping: Programmatically assign exact RBI inward remittance purpose codes (e.g., software consulting, digital marketing services, back-office operations) into metadata fields attached to every API-driven or batch-disbursed payout file.
- Algorithmic risk networks automatically audit incoming payment packets for structural data anomalies. To guarantee your automated treasury routing remains immune to abrupt ledger freezes, integrate our architectural validation framework on deploying 2-Layer API Routing directly into your operational deployment loop today.
- Domestic Clearing Execution: Disburse funds from the US corporate account via domestic ACH or Fedwire into the designated clearing partner's collection account, avoiding intermediary correspondent bank deductions.
- Decoupling outbound international payouts from correspondent banking networks requires routing high-volume business cash flows natively through established federal settlement loops. Operating within verified clearings prevents mid-transit settlement blocks on enterprise layouts. Examine the concrete architectural protocols managed via Federal Reserve Clearing Channels to safely construct your programmatic corporate disbursement networks.
- FX Conversion & Local Routing: Execute automated spot conversion at the mid-market rate and push funds across RBI PA-CB compliant AD Category-I bank channels directly into the Indian beneficiary's designated current account via NEFT/RTGS.
- Reconciliation & FIRC Archival: Harvest automated electronic FIRC and transaction ledger entries via API integration, archiving immutable audit proofs for corporate tax filings, FEMA reporting, and GST zero-rated export validations.
6. KEY COMPLIANCE TAKEAWAYS
- Optimize Beyond PA-CB Limits :- Avoid routing high-ticket invoices ($10K–$50K+) through standard retail checkout buttons or standard cross-border payment aggregators, as individual transaction limits under RBI’s PA-CB framework are capped at ₹25 Lakhs per unit of goods/services. Instead, utilize direct B2B institutional multi-currency rails or US domestic ACH routing to minimize high percentage-based processing fees and simplify clearing.
- Enforce W-8BEN-E Hygiene :- Maintain current, digitally verified IRS tax records for all Indian beneficiaries prior to capital release. Collect Form W-8BEN-E for registered corporate entities/tech agencies, and Form W-8BEN for independent contractors and individual remote developers. This dual-track onboarding protocol is mandatory for US payors to legally eliminate corporate exposure to the 30% US statutory backup withholding tax on outbound cross-border service disbursements.
- Lock Purpose Codes Upfront :- Hardcode and pre-validate the correct RBI Purpose Code at the time of invoice initiation. This ensures seamless AD bank clearing and guarantees automated, error-free eFIRA (Electronic Foreign Inward Remittance Advice) generation without payment delays.
- Protect Export Status :- Ensure all incoming remittances map directly and transparently to commercial invoices and banking records. Accurate matching is critical to safeguard the GST Zero-Rated Export classification and streamline corporate tax audits during domestic evaluations.
7. FREQUENTLY ASKED QUESTIONS (FAQ)
Q1: How does routing via US domestic clearing circumvent cross-border limits and friction?
A:Modern cross-border payment infrastructures operate under RBI’s updated PA-CB (Payment Aggregator - Cross Border) framework, which supports transactions up to ₹25 Lakh per invoice. By utilizing local US ACH/Wire clearing, the transaction is processed natively within the US banking system as a domestic transfer. The funds are then cleared upstream through wholesale institutional cross-border channels, eliminating traditional retail retail banking friction, high wire fees, and the restrictions of legacy routing
Q2: Are electronic eFIRAs/e-BRCs generated through this framework legally accepted by Indian tax authorities and GST commissioners?
A: Yes. Electronic Foreign Inward Remittance Advices (eFIRA) and e-BRCs issued via RBI-authorized AD Category-I banks carry full statutory validity under FEMA regulations. Under current DGFT and GST mandates, these electronic advices are dynamically linked with the exporter’s GSTIN and shipping bill/invoice data, making them fully compliant and seamlessly accepted for zero-rated GST refund claims and absolute proof of export-of-services.
Q3: What happens if an incorrect RBI Purpose Code is tagged to an incoming remittance?
A: Misclassified purpose codes trigger automated flags within the beneficiary bank’s reporting systems (like RBI's EDPMS), resulting in delayed settlements, mandatory compliance queries, or temporary fund freezes under FEMA regulations. The integrated API framework dynamically maps the correct purpose code based on invoice metadata, eliminating human error on the sender's side and ensuring instant compliance.
8. CONCLUSION
Optimizing cross-border treasury operations between the United States and India requires moving away from legacy retail payment gateways toward institutional, multi-currency ledger routing. By leveraging US domestic clearing infrastructure to feed RBI PA-CB compliant corridors, US founders and remote agencies eliminate exorbitant FX markups, bypass arbitrary transaction caps, and secure immutable audit trails—achieving total legal harmony across FinCEN, IRS, FEMA, and GST frameworks.
9. DISCLAIMER
This operational guide is provided strictly for educational and structural architecture purposes and does not constitute formal legal, tax, or financial advice. Cross-border capital flows, tax withholdings under Section 1441/1442, and RBI/FEMA compliances are subject to evolving regulatory mandates. Organizations must consult qualified international tax attorneys and licensed treasury advisors before deploying cross-border payment infrastructure.

Anurag Panchal
Founder & Chief Legal Strategist at ServiceMoney.in & AllRoundUpdate.com.
I specialize in Cross-Border Treasury Engineering & Dual-Jurisdiction Regulatory Architecture. My core deployment mandate is to protect multi-million dollar corporate cash flows from exposure threats, arbitrary ledger freezes, and withholding tax operational flags.
Architectural Directive: We eradicate downstream B2B payment friction by mapping outbound US banking clearings directly to active October 2026 RBI PA-CB infrastructures, automating IRS Form W-8BEN/W-8BEN-E identity tracking to legally eliminate corporate Section 1441 liabilities.
Access our technical repository at the FinTech Compliance Hub for production-ready API maps and cross-border blueprints.

